
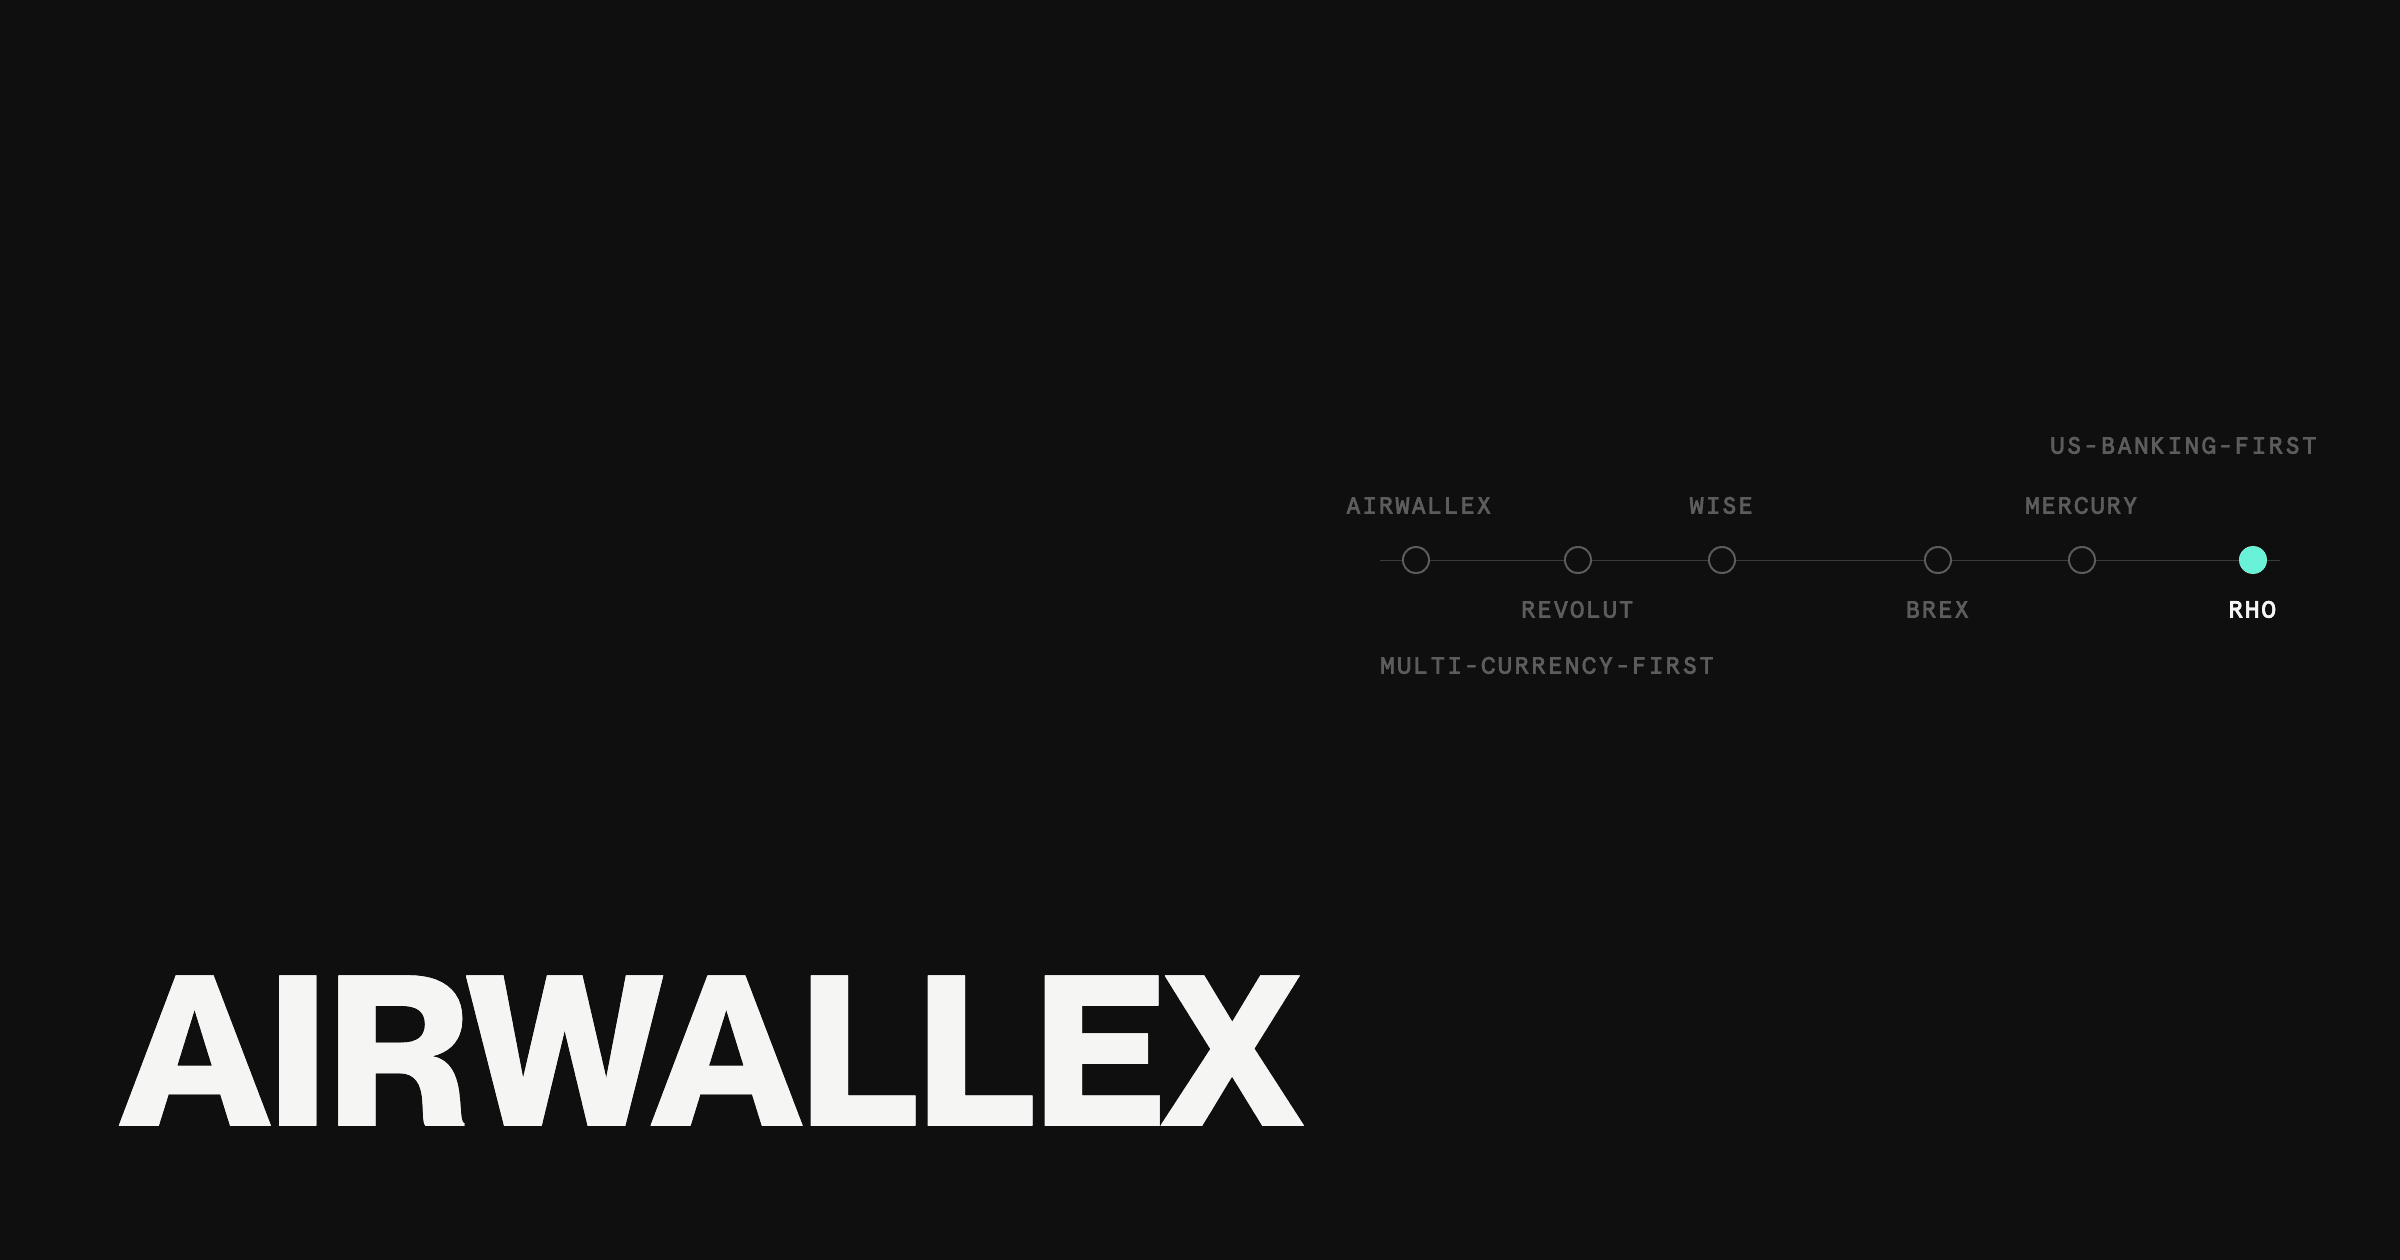
If you searched for the best Airwallex alternatives, you're probably one of two kinds of buyer.
Either your company has real cross-border volume, and you're checking what else handles multi-currency as well as Airwallex does.
Or you're a US-based business that got quoted Airwallex's per-seat-plus-scaled-fee pricing for a problem that's mostly domestic: a checking account, a card program, a way to pay vendors, somewhere to park idle cash.
Those two buyers split into two buckets:
Multi-currency-first: Airwallex, Wise Business, Revolut Business
US-banking-first: Rho, Mercury, Brex
Here's the short version, verified against each company's own site as of September 30, 2026:
Wise Business: strongest for straightforward international transfers at close to the mid-market exchange rate
Revolut Business: built for a multi-currency card with a monthly no-fee FX allowance
Mercury: good fit for simple US-first banking with occasional international wires
Brex: strongest for large card-reward tiers and fee-free domestic transfers
Rho: built for US business banking, corporate cards, Bill Pay, and Treasury, with international payments handled through a Wise US Inc. partnership rather than built natively
The split that matters most: if multi-currency operations are central to how your company moves money, start with Airwallex, Wise Business, or Revolut Business.
If your company is US-based and your banking, cards, and cash management needs outweigh how often you touch foreign currency, Rho, Mercury, or Brex fit better. The five sections below are organized along that same line.
None of these five is a full multi-currency replacement for Airwallex. That's the honest starting point. What follows is what each one is actually built for, with current pricing and fees checked directly against each provider's own pricing page rather than assumed.
Why companies look past Airwallex in 2026
Airwallex's own US pricing page lists three plans: Explore (free, up to 10 Spend users), Grow ($12/user/month plus "a platform fee scaled to team size" with no dollar figure published anywhere), and Accelerate (custom).
FX conversion runs 0.5% above interbank for major currencies and 1% for everything else. SWIFT transfers cost $15 to $25 per transfer. (airwallex.com/us/pricing, as of 2026-09-30.)
That structure makes sense for a finance team moving money across a dozen currencies every week. It's a strange fit for a 15-person startup whose only cross-border need is paying one contractor in Lisbon.
The deeper mismatch is scope, not price. Airwallex is a multi-currency payments and card platform. It isn't a US banking relationship. It doesn't replace a checking account backed by FDIC coverage, a corporate card program with real cashback, an AP workflow, or a place to earn yield on idle cash.
Companies that start on Airwallex purely for its FX rails often end up adding two or three other tools anyway.
Airwallex is also not a bank. Airwallex US, LLC is registered with FinCEN as a Money Services Business, and partners with Evolve Bank & Trust (Member FDIC) for payment services on some US accounts. Pass-through FDIC coverage is capped at $250,000, not direct coverage (per Airwallex's own account and blog pages, as of 2026-09-30).
That's a structure worth understanding, not a knock: most of the names on this list, Rho included, work the same way.
What about Payoneer and Stripe?
Both names come up constantly in the "Airwallex alternatives" conversation, so it's worth being direct about where they fit.
Payoneer charges a $29.95 annual account fee (waived once an account receives $6,000+ in a 12-month span), 1% on EU/UK bank-account and US ACH receiving, and a 0.5% fee to convert between currencies held in the account (payoneer.com/pricing, as of 2026-09-30). It's built for freelancers, agencies, and marketplace sellers collecting payouts from platforms like Upwork or Amazon, not for running a company's core banking.
Stripe charges 2.9% + $0.30 per successful US card transaction, plus 1.5% on international cards and roughly 1% more for currency conversion (stripe.com/pricing, as of 2026-09-30).
Stripe is a payment-processing platform for accepting payments, not a business bank account, a card program, or a place to hold FX balances, so it solves a different problem than Airwallex even though the two get compared constantly.
Here's the actual question to ask before comparing feature lists: how much of your money problem is genuinely multi-currency, and how much of it is "we're a US company that occasionally sends an international wire"? The five alternatives below split cleanly along that line.
Airwallex alternatives compared
Platform | Good for | Key features | Starting costs |
|---|---|---|---|
Rho | US business banking, cards, Bill Pay, and Treasury, with occasional international payments via Wise US Inc. | $0 domestic banking, cashback cards, Bill Pay at no software cost plus invoicing, $50,000 Treasury minimum, international/FX wires via Wise US Inc. | $0/month |
Airwallex | Global teams with heavy day-to-day multi-currency and FX operations | Multi-currency balances, 0.5%–1% FX markup, up to 2% card cashback on local USD spend | Free (Explore); $12/user/mo + unpublished platform fee (Grow) |
Wise Business | Companies whose main pain point is expensive currency conversion | 22 currencies held/received, card spend accepted in 231 countries, FX from 0.23%, no monthly fee, FDIC pass-through only via the opt-in Interest feature (JPMorgan Chase Bank, N.A.) | $31 one-time setup, no monthly fee |
Mercury | US-first companies wanting simple domestic banking with light international wire needs | Free/$29.90/$299 tiers, 1.5% flat card cashback, $250,000 Treasury minimum | $0/month |
Brex | Companies wanting large card reward tiers and fee-free wires | Up to 7x card rewards by category, $0 domestic and international wires/ACH/checks, MMF yield up to 4.36% | $0/user/month |
Revolut Business | Teams wanting a multi-currency card with a monthly FX allowance | 25+ currencies for send/receive, 150+ for card spend, $1,000/mo no-fee FX allowance then 0.6% | From $10/month* |
*Revolut also offers Grow and Scale tiers above Basic; their current prices could not be independently verified on revolut.com in this pass, so they are not published here. Only the $10/month Basic tier shown above was verified live on Revolut's own plan page.
Every figure above is dated and sourced in the sections below. Fees and rates change; verify current numbers directly with each provider before deciding.
Rho
Rho is a banking platform built for US companies: checking, corporate cards, Bill Pay, invoicing, expense management, and Treasury in one place, with no per-user fees.
It's not trying to be Airwallex. If your business genuinely needs to hold balances in a dozen currencies and issue local IBANs across regions, Rho isn't that product, and neither is anything else on this list that isn't Airwallex itself.
What Rho is built for: a US company that wants its domestic banking, cards, and cash management handled well, with a real but narrower answer for the occasional international payment.
Key features:
Business Checking with no monthly fees, no minimums, $0 same-day ACH, $0 domestic wires
Corporate Cards: standard cashback of 1.25% (Daily terms) or 1% (Monthly terms); up to 2% (Daily) or 1.75% (Monthly) Cashback with Rho Platinum (terms apply), on up to $1M in eligible annual card spend; no personal guarantee and no personal credit pull required
Bill Pay, included at no software cost, plus invoicing
Rho Treasury: $50,000 minimum investment, multi-asset allocation across short-duration instruments
International and FX payments: outbound wires to 200+ countries and territories in 22 currencies, provided by Wise US Inc., a 1% FX fee, and a $15 SWIFT fee that is mandatory rather than optional depending on the routing corridor
Pricing: $0/month. The core recurring charges are the 1% FX fee and, on some corridors, the mandatory $15 SWIFT fee, both limited to international transfers. (As of 2026-09-30, rho.co.)
Honest assessment: Rho earns a spot on this list for a specific buyer, not every Airwallex searcher.
If your company is US-based and your international needs amount to a handful of wires a quarter, Rho covers checking, cards, Bill Pay, and Treasury at $0/month, and still gets the wire out through Wise US Inc.'s international payments infrastructure.
Here's the tradeoff:
What Rho doesn't do is hold a balance in euros or issue a local receiving account in Singapore.
Settlement on those international wires also runs 1 to 3 business days for non-SWIFT routes and 4 to 5 business days for SWIFT, plus up to 2 additional days if a currency conversion is involved, slower than Airwallex's or Wise's same-day-to-near-instant conversion.
For a company with constant multi-currency flow, that gap matters. For a company that sends an international wire occasionally and wants everything else on one $0 platform, it usually doesn't.
See it for yourself. Get a demo →
Wise Business
Wise built its reputation on one promise: currency conversion at close to the real exchange rate, without the markup hidden in a spread. For a company whose entire complaint about Airwallex, or about a bank, is "why does moving money cost this much," Wise is one of the most transparent names on this list.
Key features:
22 currencies for holding and receiving, with card spend accepted across 231 countries and territories
FX conversion fee starting from 0.23%, varying by currency pair, at the mid-market rate with no markup, plus a volume discount above roughly $25,000 sent per month
Domestic USD wire (receiving): $6.11 flat. Outbound wire: starting from $1.13
$31 flat, one-time setup fee; no monthly fee or subscription
Optional Interest feature paying 3.4% variable APY on USD, GBP, and EUR balances
Pricing: $31 one-time setup, no monthly fee. (As of 2026-09-30, wise.com/us/pricing and wise.com/us/business.)
Honest assessment: Wise is the closest thing to "Airwallex, but simpler and cheaper for straightforward conversion." What it isn't is a banking platform. There's no corporate card program built for expense management at scale, and no Bill Pay or AP automation.
But there's a catch on FDIC claims:
On FDIC coverage, be precise: Wise itself is not a bank. The pass-through FDIC coverage up to $250,000 that Wise advertises applies specifically to the opt-in Interest feature, held at JPMorgan Chase Bank, N.A. as the named Program Bank.
Wise's own site doesn't describe that same coverage for balances outside that feature, so don't assume it extends to every dollar in a Wise Business account.
Mercury
Mercury is the name most founders already know, and it's a legitimate domestic-first alternative to Airwallex if your international needs are occasional rather than constant.
Key features:
Free tier, Mercury Plus at $29.90/month ($23.95/month billed annually), and Mercury Pro at $299/month
IO charge card: flat 1.5% cashback, unlimited, no annual fee
International wires: free with SHA fee coding; an optional $15 flat fee for OUR coding; a 1% conversion fee on non-USD wires
Domestic ACH and wires: free
Treasury: $250,000 minimum across Mercury accounts, up to roughly 3.96% net annualized yield depending on fund and tier, with a 0.15% to 0.60% annualized management fee; funds include the State Street Institutional US Government Money Market Fund (MRGXX) and the Morgan Stanley Ultra-Short Strategy Portfolio (MCRYX), held at Apex Clearing Corp with SIPC coverage up to $500,000
Pricing: Free / $29.90 ($23.95 billed annually) / $299 per month. (As of 2026-09-30, mercury.com/pricing.)
Honest assessment: Mercury's international wire terms are genuinely competitive for a US-domestic-first product, and its name recognition among startups is real. The gap against both Airwallex and Rho is the Treasury minimum: $250,000 is five times Rho's $50,000 floor, putting idle-cash yield out of reach for an earlier-stage company.
The other gap:
Mercury also isn't a natural Airwallex substitute if multi-currency is your actual need. It's a US banking product with light international wire support bolted on, not a cross-border payments platform.
Brex
Brex leans hardest into card rewards of any name on this list, and its fee schedule for basic transfer functions is aggressively free.
Key features:
Essentials plan at $0/user/month; Premium at $12/user/month; Enterprise custom
$0 on domestic ACH, international ACH, checks, domestic wires, and international wires in and out (the recipient's own bank may still charge on receipt)
Card rewards: up to 7x on rideshare, 4x on Brex Travel, 3x on dining, 2x on recurring software, 1x on everything else, structured as points rather than a flat cashback percentage
$0 foreign transaction fee on the Brex corporate card; Brex does publish a separate FX rate markup of up to 3% applied when a transaction requires currency conversion, waivable with a local-currency card in 60 countries and 30+ currencies
Cash management yield up to 4.36% via the BNY Dreyfus Government Cash Management Money Market Fund (DGVXX), tiered by balance up to $20M+; uninvested cash earns nothing
Pricing: $0 / $12 per user per month / custom. (As of 2026-09-30, brex.com/pricing and brex.com/product/cash-management-account/rates-fees.)
Honest assessment: Brex's $0 wire and ACH pricing is real and hard to beat, and the card rewards structure rewards a specific kind of spend (travel, software, rideshare) well. It isn't, however, a multi-currency account in the way Airwallex is.
Here's what's missing:
Brex does publish an FX markup, up to 3% on transactions requiring currency conversion, which runs higher than Airwallex's stated 0.5% to 1% or Wise's 0.23%, though it's avoidable using Brex's local-currency cards.
If your company's Airwallex search is driven by domestic card rewards and fee-free wires rather than multi-currency holding, Brex is a genuine option. If it's driven by FX cost specifically, Brex's published up-to-3% markup is worth weighing directly against Airwallex's 0.5% to 1% and Wise's 0.23%.
Revolut Business
Revolut's pitch is a card and account that works across a real basket of currencies, with a monthly allowance that keeps casual international spend free.
Key features:
Basic plan from $10/month, with Grow and Scale tiers available above it (current pricing not independently verified on revolut.com, so not published here)
Basic plan FX allowance: $1,000/month exchanged at the interbank rate, then a 0.6% fee on exchange over the allowance, or 1% for exchanges outside market hours
Send/receive in 25+ currencies; card spend accepted in 150+ currencies
10 no-fee local transfers per month (then $0.20 each); international transfers are $5 each with no free allowance, and SWIFT OUR coding priced separately
ATM withdrawals: 2% per withdrawal
Grow and Scale pricing could not be independently verified on revolut.com in this pass, so it is not published here. Only the $10/month Basic tier was verified live on Revolut's own plan page.
Pricing: From $10/month (Basic). (As of 2026-09-30, revolut.com/en-US/business/business-account-plans.)
Honest assessment: Revolut is one of the most Airwallex-adjacent names on this list in terms of what it's actually built for: a multi-currency card and account, not a US banking relationship.
The catch:
The Basic plan's $1,000 monthly FX allowance is a real limit worth doing the math on if your company moves meaningfully more than that in a typical month. Past it, the 0.6% (or 1% off-hours) fee applies to every dollar converted, not just the overage.
Rho vs. Airwallex: the head-to-head
Rho | Airwallex | |
|---|---|---|
Core product | US business banking, cards, Bill Pay, invoicing, Treasury | Global multi-currency payments and card platform |
Bank/FDIC status | Not a bank; checking and card services via Webster Bank, a division of Santander Bank, N.A., Member FDIC | Not a bank; Money Services Business registered with FinCEN, payment services via Evolve Bank & Trust on some accounts, pass-through FDIC to $250,000 |
International payments | Outbound only, via Wise US Inc.; 200+ countries and territories, 22 currencies (GBP unsupported for SWIFT, PKR unsupported for business payments); no multi-currency account holding | Native multi-currency balances and local receiving accounts; FX markup 0.5% (major currencies) to 1% (other currencies) |
International settlement speed | 1–3 business days (non-SWIFT); 4–5 business days (SWIFT); up to 2 additional days for conversion | Same-day to near-instant for most currency conversions |
Card cashback | 1.25% standard (Daily) / 1% (Monthly); up to 2% (Daily) / 1.75% (Monthly) with Rho Platinum (terms apply), on up to $1M in eligible annual card spend | Up to 2% on local USD spend; 0% foreign transaction fee on international card spend |
Treasury / yield | Rho Treasury, $50,000 minimum | USD yield of 3.43%–3.70% depending on plan tier (Explore/Grow/Accelerate); not a Treasury product in Rho's sense |
Bill Pay & invoicing | Bill Pay included at no software cost; invoicing included | Not a core Airwallex product line |
Pricing structure | $0/month flat | Free (Explore) to $12/user/month + unpublished platform fee (Grow) to custom (Accelerate) |
How to choose
If your company sends or holds money in more than two or three currencies on a regular basis, start with Airwallex, Wise Business, or Revolut Business, in that order of how central multi-currency is to your operation versus how much you also want a card program.
Payoneer and Stripe are worth a look too if your actual need is marketplace payouts (Payoneer) or payment processing (Stripe), rather than a bank account.
If your company is US-based, your core need is checking, cards, and cash management rather than cross-border payments, and international wires are occasional rather than constant, Rho, Mercury, or Brex fit better.
Among the three, Rho pairs Bill Pay at no software cost, invoicing, and a sub-$100,000 Treasury minimum on the same $0 platform.